Dubai property prices could fall in some segments in 2027, but no credible citywide percentage can be treated as a fact before the year happens. The question is also more complicated than it sounds: asking prices, completed sale prices and valuation indices measure different things, while an apartment competing with many new units faces a different market from a scarce family home.
As of 6 October 2026, the sensible approach is to separate observed evidence from older forecasts, then test your property against several plausible outcomes. That gives a buyer or owner a decision framework without pretending to know the market’s exact turning point.
Start with dated evidence, not a recycled headline
ValuStrat’s August 2026 residential report page reports a citywide valuation index of 218.8, down 0.2% month on month and 3.1% year on year. It reports annual declines of 1.7% for villas and 5.3% for apartments. These are valuation-index observations for the covered market, not a statement that every home fell by those percentages.
The small monthly movement and negative annual comparison can both be true. The first describes the latest month; the second compares with a different point twelve months earlier. Neither, by itself, establishes what will happen throughout 2027.
For an individual purchase, look beneath the citywide number. A transaction comparison should match location, unit type, condition, completion status and other material features. City averages can change because the mix of properties sold changes, even when like-for-like values behave differently.
Read forecasts with their original dates attached
In May 2025, Reuters reported Fitch’s expectation of a correction of no more than 15% during the second half of 2025 and 2026, linked to a large planned delivery pipeline. That was a forecast for that period, not a fresh prediction of a 15% fall in 2027.
At the start of 2026, ValuStrat’s published outlook instead projected around 10% residential capital growth for 2026 and broadly flat rents. Its stated pipeline was 131,234 units, while warning that delivery dates could change. Those figures belong to an earlier forecast, not to a verified completed-supply total or a current 2027 baseline.
The contrast is useful. Reputable forecasts can differ because they use different assumptions, timing and measures. New evidence can also overtake an outlook. Choosing whichever headline supports a purchase already planned is not analysis.
For any forecast, record its publication date, geographic scope, price measure and assumptions. Then ask what has changed since it was issued.
The supply pipeline is not the same as delivered homes
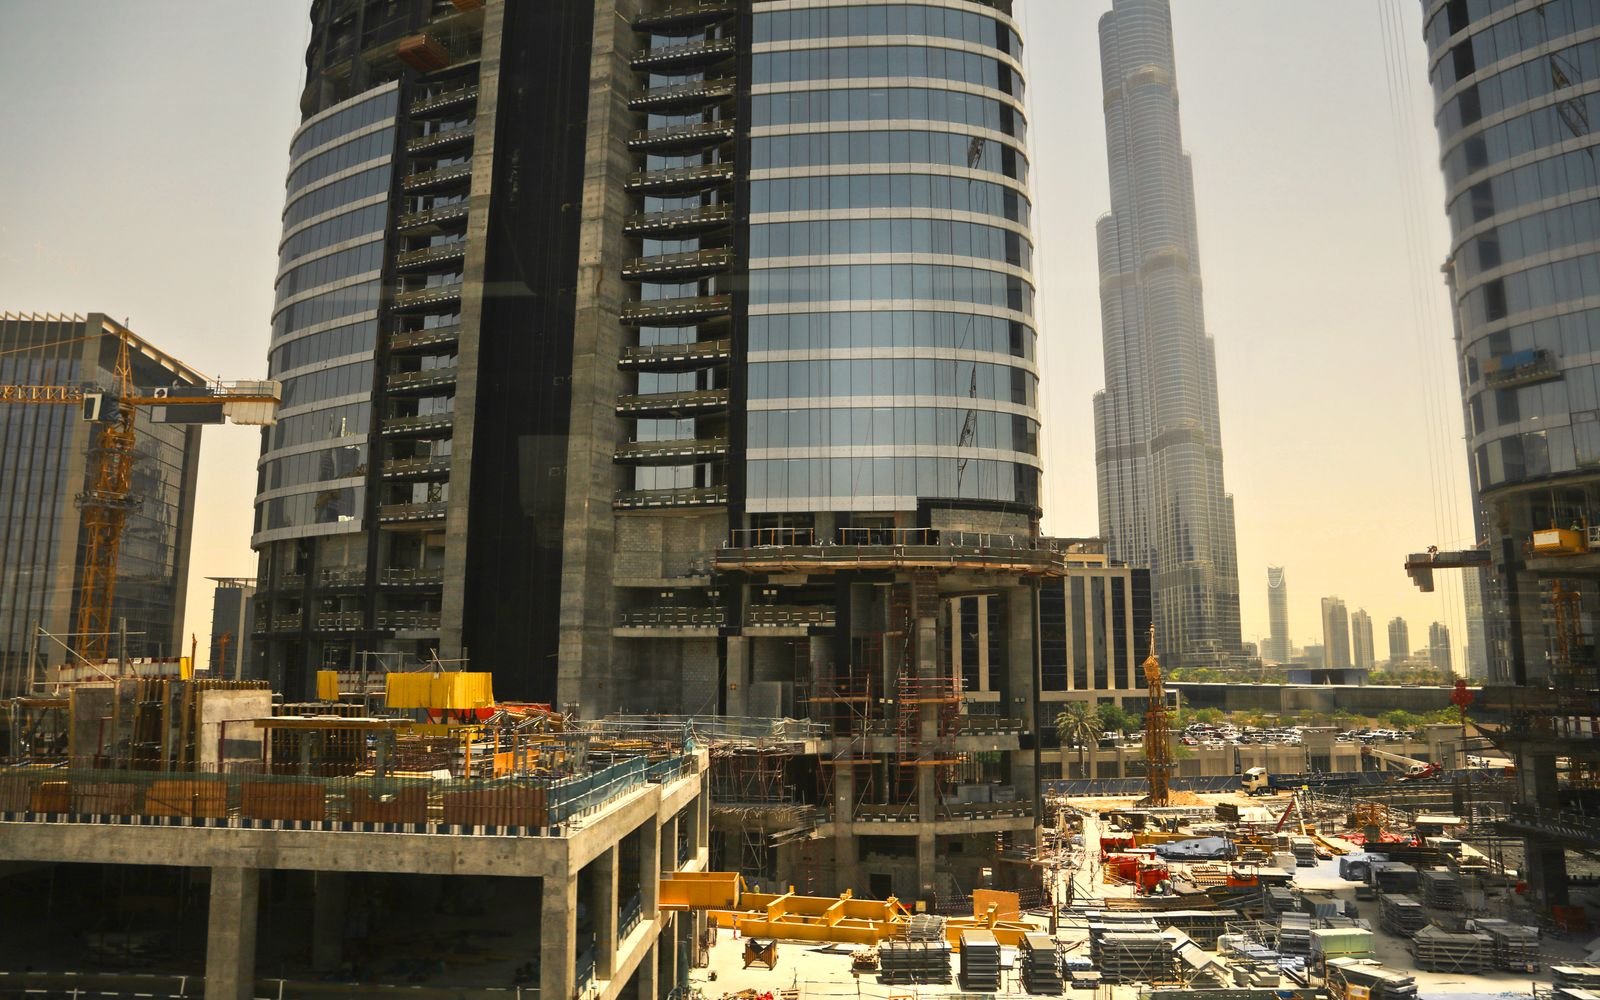
A newly announced project, an active construction site, a completed building and an occupied apartment represent different stages. Adding every planned handover together can exaggerate the homes immediately available to tenants. Ignoring the pipeline entirely can understate the competition a future seller or landlord may face.
For a specific development, use DLD’s Project Status Enquiry to review registered information and completion progress. Combine that with the contract and current developer documentation. A completion percentage is helpful evidence; it is not a guarantee of a precise handover date or immediate leasing readiness.
Timing cuts both ways. Delays may reduce near-term competition, but can also postpone a buyer’s rental income and concentrate deliveries in a later year. A household expecting to move in may need extra rental accommodation while waiting.
Examine the competing homes around your property, not only the emirate-wide count. Ten similar towers in one leasing catchment can matter more to a particular apartment than a much larger number of different homes elsewhere.
Demand must be measured against the right stock
Population growth alone does not translate directly into demand for every property. Household size, income, location preferences and the balance between renting and owning affect what accommodation people choose. A growing city can still have oversupply in a particular unit category or price band.
Likewise, strong tourism does not automatically fill every privately operated short-term apartment. The property must compete on location, quality, pricing and operating execution, within the relevant rules. Corporate expansion may support some employment districts without lifting every suburban asset equally.
For a landlord, useful evidence includes comparable signed rents, time to secure a tenant, competing vacant units and incentives. For a seller, it includes completed transactions, genuine viewing feedback and the gap between asking and agreed prices. DLD’s open-data resources help ground the transaction side of that assessment.
Do not confuse resilience with immunity. A desirable home can be easier to rent or sell while still experiencing a lower price when financing conditions or buyer confidence change.
Build three scenarios for 2027
The following are planning scenarios, not Nova Domus price forecasts. Their purpose is to make the consequences of uncertainty visible before you commit money.
| Scenario | Conditions to watch | Practical response |
|---|---|---|
| Firmer market | Demand absorbs actual completions; comparable rents and sales stabilise or improve | Preserve price discipline; do not assume every premium is justified |
| Broadly stable market | Supply and demand roughly balance, with differences between districts | Focus on operating income, transaction costs and holding period |
| Softer market | Deliveries and resale competition rise faster than relevant demand | Keep liquidity, stress-test rent and avoid a forced short-term exit |
Use numbers on your own property. A hypothetical AED 1.5 million home would be worth AED 1.35 million after a 10% decline. That is a scenario, not a predicted valuation. Selling would involve further transaction costs, so the reduction in net proceeds could exceed the headline price fall.
Leverage magnifies the equity effect. If the same home had AED 900,000 of debt outstanding at the comparison date, gross equity would fall from AED 600,000 to AED 450,000 before selling costs: a 25% reduction. Keep the assumed debt balance fixed to understand the example; actual repayments, interest and fees change a real outcome.
Stress-test rent separately. Falling values do not guarantee unchanged rent, and a higher calculated gross yield can simply reflect a lower asset value rather than stronger operating performance.
Translate uncertainty into a buying or holding decision
For an owner-occupier, begin with the expected holding period, monthly affordability and the value of having a suitable home. Buying is harder to justify when it requires a quick resale at a higher price to remain affordable. A longer intended stay may reduce dependence on next year’s valuation, but it does not eliminate financial risk.
For an investor, write down the minimum rent needed to cover operating costs and financing, the vacancy reserve and the amount available for repairs. Check whether the investment still makes sense without capital appreciation. If it only works under the strongest scenario, the purchase is more speculative than its presentation may suggest.
For an off-plan buyer, map remaining instalments and handover costs without assuming an assignment sale. Understand resale conditions and the consequences if funding or mortgage approval is less favourable than expected.
For an existing owner, a market forecast alone is not a reason to sell. Compare the realistic net proceeds from selling with the income, costs and risks of holding. Personal liquidity needs can matter more than a disputed citywide prediction. Keep general market commentary separate from a current, property-specific valuation and use sources dated to the decision you are making.
Apply each scenario to the property options actually available at your budget, rather than forecasting the whole city to justify one purchase. Our Dubai buying guide explains the practical checks needed regardless of the market outlook.
Frequently asked questions
1. Will Dubai property prices definitely fall in 2027?
No. The outcome is uncertain and likely to differ across properties. Available 2026 evidence and older forecasts help identify risks, but they do not establish a verified 2027 result or a single percentage applicable to every home.
2. Did Fitch predict a 15% fall specifically for 2027?
The May 2025 Reuters report cited a forecast for the second half of 2025 and 2026. Reusing that number as a new 2027 prediction changes its meaning. Always retain the original period and publication date.
3. Does a large pipeline guarantee oversupply?
No. Completion timing, unit types, locations and demand all matter. However, the pipeline remains relevant: competing homes can affect rent and resale prospects even if the citywide market appears balanced.
4. Are villas protected from a correction?
No asset type is automatically protected. ValuStrat’s August 2026 data showed differing villa and apartment performance, including a negative annual villa reading. The specific community, property condition, price and buyer pool remain essential.
5. Should I wait until the market reaches the bottom?
A precise bottom is usually clearer afterwards than beforehand. Set affordability and valuation criteria instead. Waiting may be sensible when the funding plan is weak or the asking price lacks support; buying can be considered when the home works under conservative assumptions.
Make a decision that can survive more than one outcome
The right response to uncertainty is a stronger purchase or holding plan: relevant comparables, manageable debt, adequate reserves and no dependence on an immediate resale profit.
Speak with Nova Domus about a property-specific assessment. Bring the asking price, expected rent, financing terms and intended holding period so the discussion can move from a market headline to a decision you can evaluate.